Why it took over
Three reasons, in order of importance. It clears in real time, including weekends and public holidays, which no other bank rail in this country does. It is not a card, so it does not hit the gambling decline logic that stops most card deposits to offshore merchants. And it is free at both ends — banks do not charge for NPP transfers.
From the casino’s side it is equally attractive: instant settlement, no chargebacks, and an Australian bank account at the other end that has already been identity-checked by somebody else.
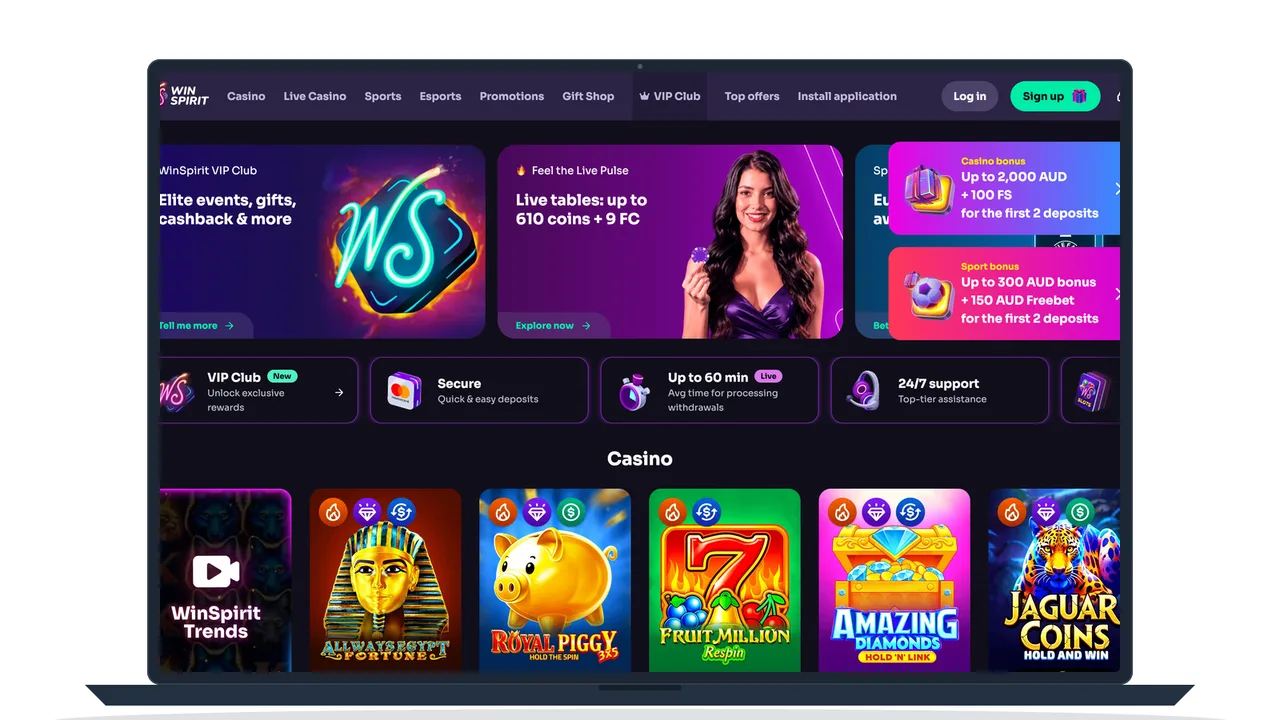
Deposits are easy. Payouts are the test.
Here is the distinction that decides which site you should use. Taking PayID in is trivial for an operator — it is receiving a bank transfer. Sending PayID out means holding an Australian bank account capable of paying customers, and a meaningful number of offshore casinos do not have one. They accept PayID and pay out in Bitcoin.

That is legal, it is disclosed in the terms, and it is not what most people assume when they see the PayID logo on the deposit page. Check the withdrawal tab specifically, before you deposit.
The PayID logo on a casino’s homepage tells you how the money gets in. The withdrawal tab tells you how it gets out. Only the second one is your problem.
Every operator in our tables goes through the same four steps, in the same order. We grade what actually happens, not what the casino promises on its landing page. Criteria, weightings and the reasons an operator gets left out
How we test every casino
How a PayID deposit works
- You choose PayID in the cashier and enter an amount.
- The site shows you a PayID — an email address or phone number — and a reference code.
- You open your banking app, pay that PayID, and put the reference in the description field.
- The transfer lands in seconds. The casino usually credits within a minute or two.
The reference code is the part people skip, and skipping it is how a deposit goes missing for a day. Without it the operator cannot match your payment to your account and somebody has to do it by hand.
One more thing worth noticing: the PayID you are paying often belongs to a payment processor rather than to the casino, and it can change between deposits. Always copy it fresh from the cashier rather than saving it as a payee.
Times I measured
| Stage | Fastest | Slowest |
|---|---|---|
| Deposit credited | 40 seconds | 6 minutes |
| Withdrawal approved | 10 minutes | 24 hours |
| Funds in my account after approval | 25 seconds | 2 minutes |
Every slow figure in that table is the casino, not the rail. That is consistent with everything in fast withdrawal casinos: the approval is the variable, the transfer is not.
Limits and the bank’s view
Most banks apply a daily NPP limit, commonly $1,000 to $10,000 depending on the institution and whether you have raised it yourself in the app. Casinos apply their own minimums, usually $10 to $20, and per-transaction caps on the way out. Where the two collide, the lower one wins and the difference lands as a second payment.
Your statement will show a transfer to a business or individual name rather than a casino. That means an in-app gambling block will not necessarily catch it — worth knowing if you are relying on one, and covered in responsible gambling.
Frequently asked questions
Is PayID safe to use with an offshore casino?
The rail is as safe as any bank transfer and cannot be reversed, which cuts both ways: it is final. The risk is not PayID, it is whether the operator pays you back — which is what the rest of this site is about.
Why did my PayID deposit not appear?
Nine times out of ten the reference code was left out or mistyped. Contact support with the transfer receipt and it gets matched manually, usually within a few hours.
Can I withdraw by PayID if I deposited by card?
Often yes, and some sites prefer it. You will generally need to verify the account first, since the name on the bank account has to match the account holder.